Non residents are typically offered 60 to 70 percent of the bank's valuation, residents up to 80. Terms usually run 20 to 30 years. Budget 10 to 12 percent of the price for taxes and fees on top of the deposit. Approval normally takes four to eight weeks, so start before you are under pressure.
Most buyers we meet assume the mortgage will be the hard part. It usually is not. What catches people out is the gap between the price of the house and the amount of cash they actually need on the day.
The important number is loan to value, and it depends on your residency.
Note that it is a percentage of the bank's appraisal, not the price you agreed. If the valuation comes in below the purchase price, the shortfall is yours to cover, and that surprise has ended more than one purchase.
Terms usually run 20 to 30 years, with age limits at the end of the term that can shorten the maximum for older borrowers.
Put the two numbers together before you start viewing.
As a non resident on a 70 percent mortgage, you need 30 percent as a deposit, plus roughly 10 to 12 percent of the price for taxes and fees. That is somewhere around 40 percent of the purchase price in cash. Work from that figure, not from the deposit alone.
Indicative figures. Confirm the current rates for your region and property before budgeting.
Plan for four to eight weeks from application to approval. Start before you find the property, not after, because a seller will not usually wait two months while you arrange finance.
Spanish variable rates are generally tied to Euribor, which means your payment moves with it. Fixed costs a little more at the outset and does not move.
There is no universally right answer. The honest version is that if a rate rise of a couple of points would cause you a genuine problem, take the fixed rate and treat the extra as insurance. If you have headroom and intend to repay early, variable may suit. Ask the bank specifically about early repayment charges, because they differ a lot between products.
Spanish banks price non resident mortgages quite differently from one another, and the published rate is not always the rate you get. A broker who places these regularly knows which banks are lending to people in your situation this month, which is not something you can tell from a website.
We manage property, we do not sell mortgages, and none of the above is financial advice. Rates, lending criteria and tax rates change frequently. Use a qualified mortgage broker and a Spanish lawyer, and confirm every figure here against what is actually on offer when you apply.
If the plan is to let the property out and have the rental income contribute to the mortgage, we can tell you what that income realistically looks like across a year before you commit to the repayments. Message us on +34 658 235 481 or info@casacapitals.com.
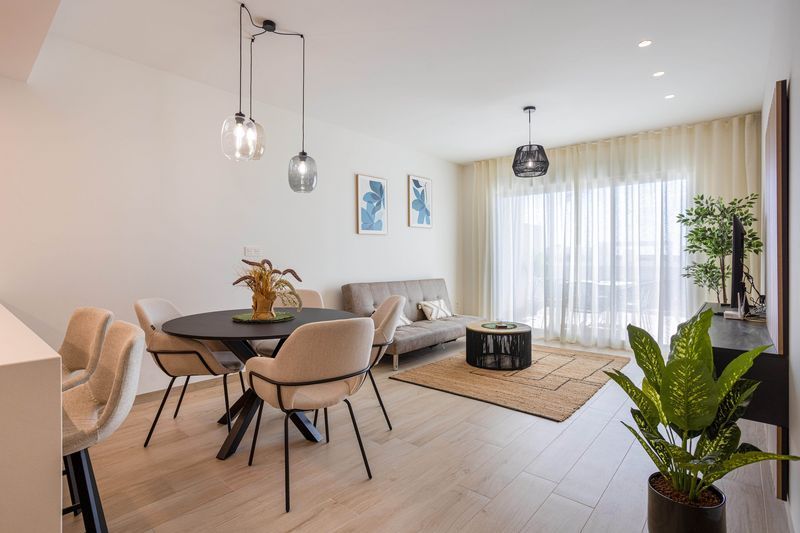
A couple of the properties we actually manage on the Costa Blanca.
We have managed 50+ homes on the Costa Blanca from our base in Orihuela Costa. Ask us anything about yours.
Four ways we work with owners, buyers and guests across the Costa Blanca.
We run the whole letting operation for you: listings, pricing, guests, cleaning and clear reporting.
Buying or selling on the Costa Blanca, guided by a team that manages property here every single day.
Browse the homes we look after and book your stay direct with the people who run them.
Maintenance, seasonal checks and repairs for owners who cannot be here to handle them.
Send us the address and a few photos and we will come back with what we would expect it to earn, and what we would change to get there.
Choose which categories of cookies we are allowed to use. Necessary cookies are always on because the site cannot function without them. See our Cookie Policy for full details.